Getting Home Loans for Travel Nurses: A Systematic Review of Mortgage Accessibility Barriers. A loan as a tour nurse? Learn why creditors hesitate, how stipends and contracts are treated, and the way to prepare.
A Systematic Review of Mortgage Accessibility Barriers: Home Loans for Travel Nurses
Introduction
A tour nurse I realize had sturdy earnings, a wholesome financial savings account, and a smooth credit score history. Her first loan communique nonetheless went sideways. The mortgage officer checked out her pay stubs, noticed 3 special employers` names, an opening among contracts, and a huge proportion of her pay arriving as stipends, and she or he left that assembly satisfied she turned into “unmortgage able.” She wasn’t. She turned into unprepared for a way a lender reads a tour nursing paper trail.
If you are studying domestic loans for tour nurses, the query is why approval may be more difficult for you than for a workforce nurse income less, and what you could do approximately it. The brief solution is that creditors underwrite balance and documentation, and tour nursing appears risky on paper even if it isn’t. This publish explains the not unusual place obstacles, how earnings are usually evaluated, and the way to prepare. I’m a nurse educator, now no longer a loan professional, tax advisor, or economic advisor, so deal with this as a framework for asking higher questions.
Quick Answer
The maximum not unusual place obstacles are a brief or fragmented employment history, earnings that consists of tax-loose stipends creditors might not completely count, gaps among contracts, variable hours, and occupancy regulations that expect you may stay withinside the domestic. Most of those may be addressed with documentation, a lender skilled with settlement or variable-earnings borrowers, and cautious timing. Rules range via way of means of mortgage software and lender, so affirm cutting-edge suggestions directly.
A Note at the Word “Systematic Review”
A systematic overview follows a documented protocol: a described query, searches throughout more than one reassesses, inclusion criteria, based screening, pleasant appraisal, and obvious synthesis, normally suggested the use of PRISMA.
I have not performed one, and this identify suits the subject poorly. There are little peer-reviewed studies on loan get entry to for tour nurses specifically. What exists is lender suggestions, organization promoting guides, enterprise articles, and anecdote. A proper overview might want to deal with the ones files as reassess and be express approximately their pleasant.
If you need to apply the label, outline you reassess, record the way you screened them, and say what you could not get entry to.
How Lenders Think
Underwriting comes down to 3 questions. Can you repay, which means is your profits enough and probably to continue? Will you repay, which means what does your credit score records display? And do the assets steady the mortgage adequately? Travel nursing usually increases the primary question.
Lenders historically need proof of regular profits, regularly searching at a -12-month records and averaging variable income. A workforce nurse with one business enterprise and a W-2 indicates that cleanly. A tour nurse might also additionally display numerous staffing agencies, specific states, and pay that varies with the aid of using contract. In me enjoy advising nurses, the clinicians who warfare are hardly ever underqualified. They`re below documented.
Barrier One: Employment History That Looks Fragmented
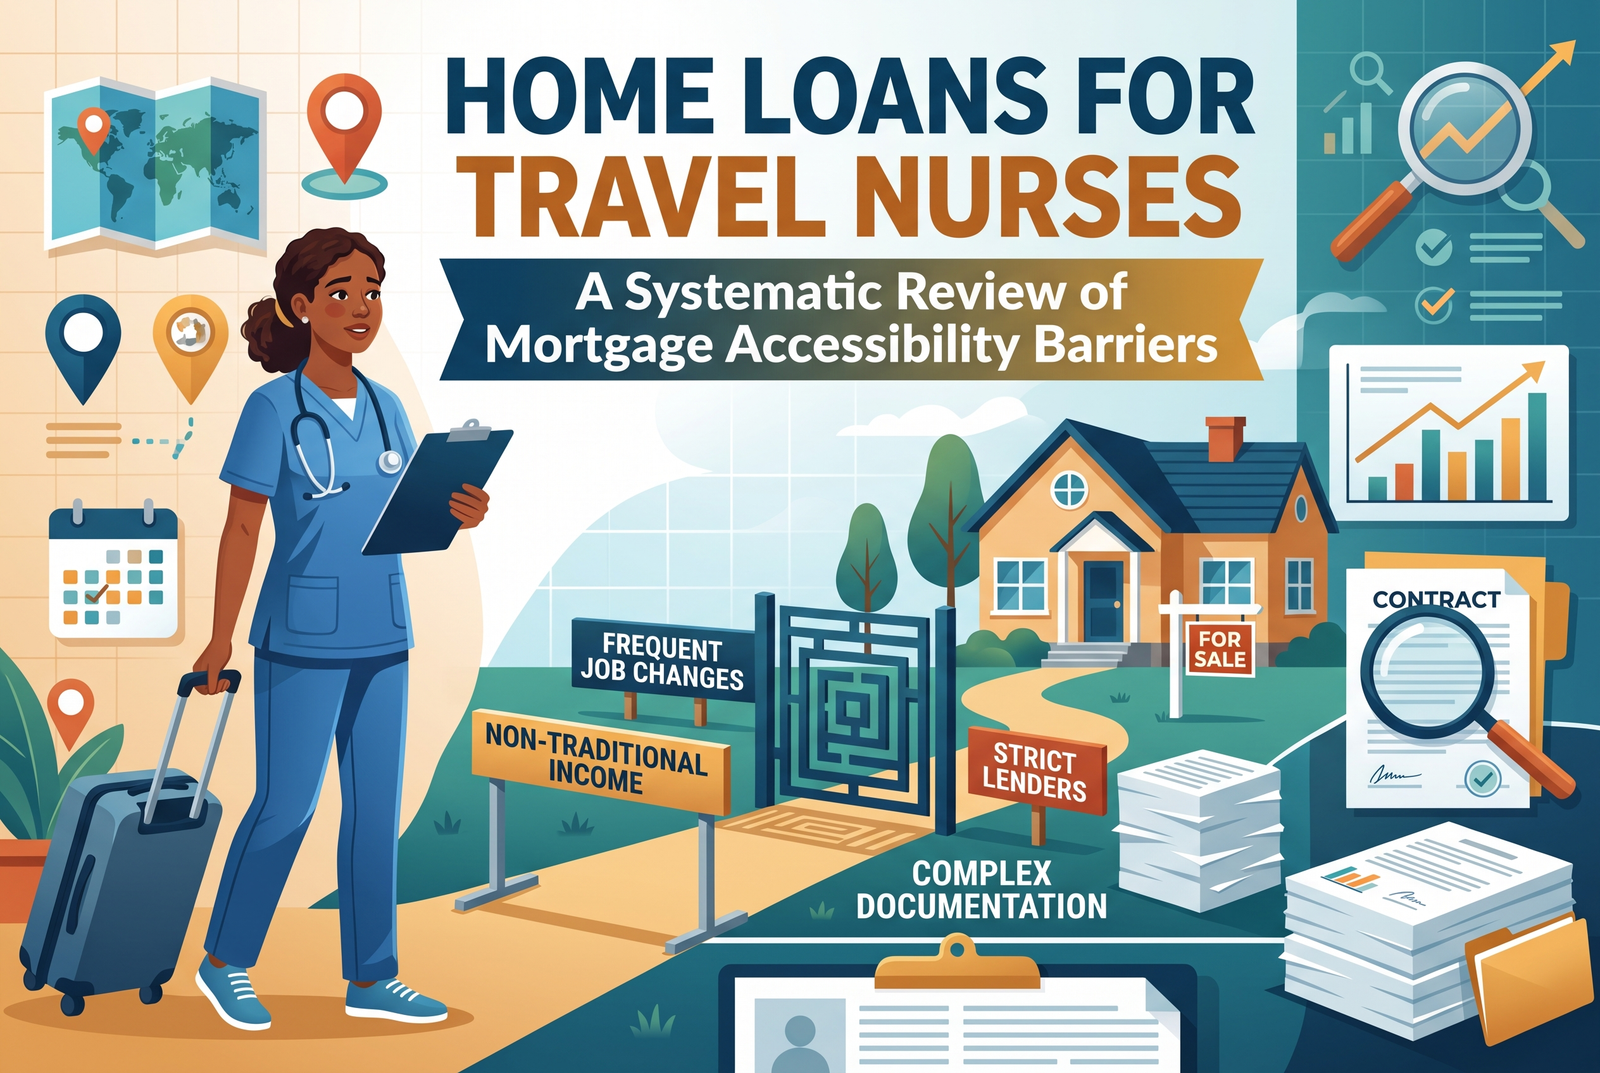
Multiple employers over years can study as instability even if you have labored constantly with inside the identical profession. Many creditors recognition on continuity inside a field, and a few recommendations permit for this, however character underwriters’ range. Ask creditors immediately how they deal with the identical career throughout specific staffing agencies.
Barrier Two: Stipends and Income Calculation
This is the largest technical problem. Travel nurse pay is regularly cut up among a taxable hourly salary and non-taxable stipends for housing and meals. Lenders might also additionally calculate qualifying profits from the taxable portion, because is what seems reliably on tax returns, and deal with stipends conservatively or exclude them. That could make your qualifying profits appearance plenty decrease than your real coins flow.
Some creditors and applications won’t forget stipends below sure conditions, along with documentation of a steady records and proof that the profits are probably to continue. Practices range widely, so ask every lender how they deal with non-taxable stipends and what files they require.
There’s additionally a tax problem well worth understanding. Stipends are normally tax-unfastened simplest in case you hold a valid tax domestic below IRS rules, and a tax marketing consultant must affirm that your situation qualifies. Lenders reviewing your tax returns might also additionally see this too.
Barrier Three: Gaps Between Contracts
Taking some weeks off among assignments is common, and it seems on paper as an opening in profits. Underwriters might also additionally ask for explanations, and a sample of lengthy gaps might also additionally lessen the profits they may be inclined to count. Keep facts displaying while contracts commenced and ended and be organized to explain your sample plainly. Some debtors additionally hold coins reserves, that can reassure creditors and assist in any case.
Barrier Four: Variable Income and Averaging
When profits vary, creditors regularly common it over a period, typically years, that can pull your qualifying wide variety down in case your income lately rose, because early decrease years drag the common. Pay can swing with crisis-charge contracts and marketplace conditions, so creditors can be careful approximately latest spikes. Understand how your lender averages and whether latest will increase could be recognized.
Barrier Five: Occupancy and the Reality of Travel
If you`re shopping for a number one residence, mortgage packages commonly anticipate you to occupy it inside a fixed length and for a minimal time. For a person who spends maximum of the yr on assignment, that may be an actual tension. Some guests purchase a domestic they go back to among contracts, which may be legitimate, even as others recall funding property, which has distinctive rules, fees, and down charge requirements. Be sincere together along with your lender approximately your plans, due to the fact misrepresenting occupancy purpose could have critical consequences.
Here is one region I’ll provide an opinion: being candid with the mortgage officer early saves anyone trouble. If your plan is murky, paintings it out with an expert earlier than you follow, now no longer while underwriting.
Barrier Six: Down Payment, Reserves, and Debt
These follow to anyone however can rely greater for travelers. Lenders have a take a observe debt-to-earnings ratios, credit score scores, and financial savings. Travel nurses frequently have sturdy coins float however might also additionally maintain financial savings fragmented, deliver prices in places, or have costs which includes reproduction housing that influence how cushy they feel. Gathering easy financial institution statements and displaying steady financial savings helps.
Loan Programs Worth Knowing About
Several kinds exist, and eligibility varies. Conventional loans comply with organization hints and frequently paintings properly for debtors with sturdy credit score and documentation. FHA loans have distinctive qualification requirements and can in shape a few debtors. VA loans are to be had to eligible veterans and carrier members, and a few nurses qualify thru army carrier. Some creditors provide non-certified loan options, which include financial institution declaration or different opportunity documentation loans, that may accommodate uncommon earnings however frequently deliver better fees or large down payments.
Alternatives aren’t robotically higher or worse. Compare overall cost, now no longer simply approval odds, and study phrases carefully.
Comparing Barriers and Responses
| Barrier | Why lenders worry | Possible response | Question to ask |
| Multiple employers | Looks unstable | Show continuous work in the same field | How do you treat agency changes in one occupation? |
| Stipends | Not reliably documented as income | Provide history and documentation | How do you count non-taxable stipends? |
| Gaps between contracts | Income interruptions | Records and an explanation, plus reserves | How long a gap triggers concern? |
| Variable income | Hard to predict | Show a stable multi-year pattern | How do your average earnings? |
| Occupancy | Primary residence expectations | Be candid, consider alternative strategies | What are the occupancy rules for my plan? |
Strategies That Often Help
Work with a loan officer who regularly handles contract and variable-income borrowers and ask how many travel clinicians they’ve closed. Organize documents early: two years of tax returns, W-2s or 1099s, contracts, pay stubs, and bank statements. Keep a clear timeline of assignments. Build reserves. Avoid new debt or large purchases before closing. Consider timing, because a period of continuous work before applying can strengthen your file. And get pre-approved before shopping but remember that pre-approval isn’t final approval. Consult a tax professional about your tax home and stipend treatment.
Advantages and Limitations of Buying as a Travel Nurse
Owning a home can provide stability, a base between contracts, and in some cases support for a legitimate tax home, though that determination depends on facts a tax professional should review. The limitations are real. You carry costs while away, vacancies and maintenance require management, selling can take time, and a mortgage commits you to payments even if contract availability drops. Travel nursing demand has swung noticeably in recent years, so think hard about how a downturn would affect you.
How to Decide
Start with whether you need a number one house, a base, or a funding. Estimate affordability the usage of conservative earnings, that means taxable wages and a pessimistic assumption approximately settlement availability. Compare creditors` remedy of stipends. Check your credit score and savings. Talk to a loan expert, and for tax questions, a certified tax advisor. I’m now no longer capping a position to inform you whether shopping for is proper for you, because relies upon to your budget and threat tolerance.
Expert Tips
Interview a couple of creditors earlier than making use of formally, on account that regulations differ. Ask for recommendations in writing. Keep earnings documentation steady from settlement to settlement. Don’t commingle non-public and reimbursed costs confusingly. Consider speaking with different vacationers approximately creditors who have labored properly for them, even as remembering that man or woman effects vary. Recheck policies earlier than making use of, on account that recommendations and marketplace situations change.
FAQs
Can tour nurses get a loan?
Yes, many do. The undertaking is documentation and the way creditors deal with employment records and stipends.
Do creditors rely on tour nurse stipends as earnings?
It varies. Some rely on them conservatively or handiest with documented records, and others exclude them. Ask every lender.
How lengthy do I want to be a tour nurse earlier than making use of?
Lenders frequently opt for a -yr records with inside the field, however practices differ. Verify with the lender.
Can I purchase a domestic if I’m not often there?
Primary-house loans deliver occupancy expectations, so be candid and discover alternatives along with funding belongings with a expert.
Is financial institution assertion loans an awesome idea?
They can assist with uncommon earnings however frequently fee more. Compare phrases carefully.
Conclusion
So, why is it difficult to get domestic loans for tour nurses, and what helps? Lenders need stable, documented, predictable earnings, and tour nursing can appearance fragmented on paper, mainly with stipends, gaps, and converting employers. The repair is generally preparation: prepared records, a lender who is aware settlement work, sincere occupancy plans, and conservative budgeting. This week, collect years of documents, name 3 creditors with the equal questions on stipends and employment records, and communicate with a tax expert approximately your tax domestic.
Read More:
https://nurseseducator.com/didactic-and-dialectic-teaching-rationale-for-team-based-learning/
https://nurseseducator.com/high-fidelity-simulation-use-in-nursing-education/
First NCLEX Exam Center In Pakistan From Lahore (Mall of Lahore) to the Global Nursing
Categories of Journals: W, X, Y and Z Category Journal In Nursing Education
AI in Healthcare Content Creation: A Double-Edged Sword and Scary
Social Links:
https://www.facebook.com/nurseseducator/
https://www.instagram.com/nurseseducator/
https://www.pinterest.com/NursesEducator/
https://www.linkedin.com/company/nurseseducator/
https://www.linkedin.com/in/afzalaldin/
https://www.researchgate.net/profile/Afza-Lal-Din
https://scholar.google.com/citations?hl=en&user=F0XY9vQAAAAJ